Tariff barriers and traceability impede Vietnamese seafood exports
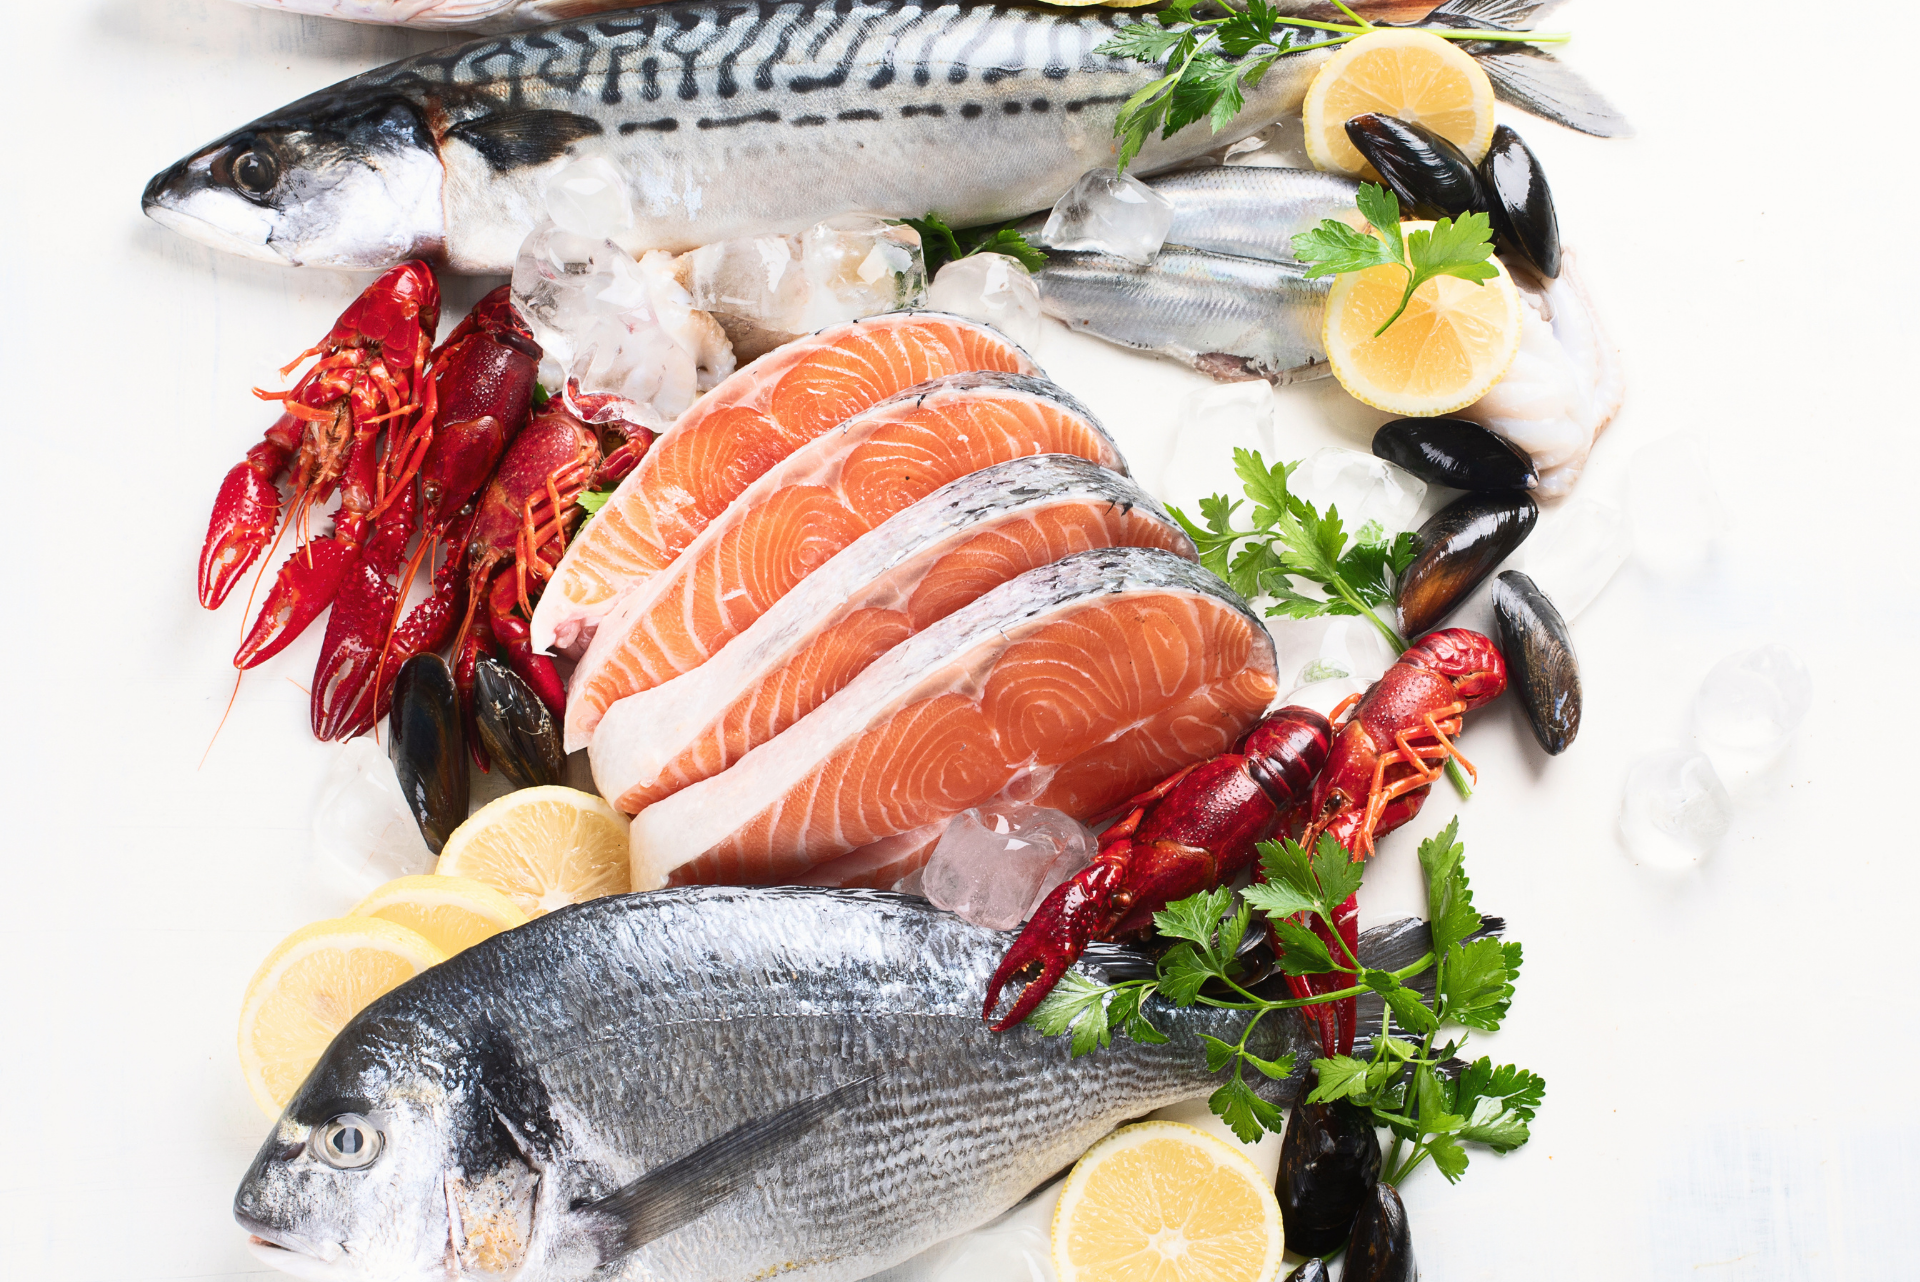
Vietnamese seafood exports continued to expand over the first 8 months of 2026, but the growth momentum is decelerating as the US and EU markets soften. In the closing months of the year, trade duties, anti-dumping tariffs, and traceability mandates are projected to directly impact order volumes, operating expenses, and enterprise competitiveness.
Shrimp leads, but pressure mounts on q4
According to Ms. Le Hang, Deputy Secretary-General of the Vietnam Association of Seafood Exporters and Producers (VASEP), Vietnam's seafood exports reached 1.14 billion USD in August 2026, up 6% year-on-year; cumulative 8-month export turnover reached 8 billion USD, an 11.8% increase. However, this growth pace represents a slowdown compared to the 12.8% recorded in the first 7 months.
Robust growth in China–Hong Kong and ASEAN is offsetting weakness in the US, EU, and parts of Japan. This divergence is expected to become more pronounced in Q4 as trade tariffs and traceability requirements take a direct toll on purchase orders.
Exports to China–Hong Kong remain the primary growth engine, reaching 287.7 million USD in August (up 26.2%) and climbing to 2.03 billion USD over the 8-month period (up 33.4%), accounting for 25.35% of total export turnover. This single market contributed an additional 508.61 million USD—representing 60.17% of total industry growth—driven by demand for shrimp, pangasius, crab, and marine fish.
Conversely, August exports to the US fell 11.4% to 167.74 million USD, keeping the 8-month total flat at 1.24 billion USD. Shrimp and pangasius dropped substantially, while tuna, crab, and mollusks posted gains.
The EU declined 1.6% over the 8 months down to 749.9 million USD, pulled down mainly by sluggish shrimp and tuna shipments. Japan edged up 2% to 1.11 billion USD; South Korea rose 4.9% to 566.3 million USD. ASEAN reached 544.9 million USD, up 20%—with August alone surging 31%.
In August, shrimp exports reached 485.5 million USD (up 5.7%), bringing the 8-month total to 3.29 billion USD (up 12.3% and accounting for roughly 41% of total seafood exports). China–Hong Kong served as the main anchor at 1.13 billion USD, up 37.6%. In August, shipments rose across Japan (+10%), South Korea (+16%), and ASEAN (+48%).
In contrast, shrimp exports to the US in August plummeted 22% to 70 million USD, lowering the 8-month total by 13.4% to 427.6 million USD. The EU shrank 18% in August and 2.7% cumulatively.
This stems from a 12.5% US Section 301 tariff—above the 10% rate levied on select competitors—which widens the price disadvantage, compounded by sharply higher preliminary anti-dumping duty determinations.
Final determinations expected in late September will dictate Q4 order volumes; sustained high duties will accelerate trade diversion into Asia and depress selling prices further.
Pangasius shipments reached 194.8 million USD in August (+0.4%), totaling 1.5 billion USD across 8 months (+9%). China–Hong Kong expanded 26.5% to 435.21 million USD. The EU climbed 42.04% in August and 11.4% cumulatively to 131.7 million USD, aided by wild whitefish supply shortages in Europe and high cod prices.
The US proved the weakest link: August shipments fell 54.8% to 12.5 million USD, bringing the 8-month total down 13.9% to 201.7 million USD. Unfavorable final POR21 review results released on August 12—featuring substantial anti-dumping duty increases—have prompted buyer caution. A swift US rebound remains unlikely; growth will hinge on China, the EU, ASEAN, the Middle East, and niche destinations.
Tuna: August exports declined 11% to 78.1 million USD, with the 8-month figure inching up just 0.5% to 622 million USD. While the US gained 8% to 247.7 million USD, the EU dropped 20% to 113.6 million USD (plunging 43.6% in August alone). Raw skipjack tuna prices in Bangkok rebounded, while tariff preference competition and origin rules in the EU squeezed margins. ASEAN grew 30.7% in August, yet lacks the scale to replace these two primary markets.
Crabs and Other Crustaceans: Served as a positive bright spot, reaching 55 million USD in August (+50.7%) and 304.9 million USD across 8 months (+34%). US shipments doubled to 84.7 million USD; China–Hong Kong rose 41.8% to 154.7 million USD. The US recognition of comparability for Vietnam's swimming crab fishery and the court dismissal of related litigation have mitigated legal uncertainty.
Trade tariffs to dictate year-end orders
According to VASEP, from September through year-end 2026, seasonal holiday demand and inventory replenishment cycles may sustain high export values, but policy risks will determine the structure of growth.
For shrimp, the late-September anti-dumping review outcome alongside Section 301 tariffs will govern US purchase orders, quote pricing, and the speed of market redirection. For pangasius, heightened anti-dumping duties dampen US prospects, leaving the EU and China as essential compensating buffers.
For wild-caught seafood including tuna, squid, and octopus, the EU's IUU yellow card, the CATCH digital certification system, and stricter traceability requirements will constrain order fulfillment.
In the US, import rules under the Marine Mammal Protection Act (MMPA) requiring admissibility documentation for flagged tariff lines serve both as a technical barrier and a supplier-screening mechanism. While swimming crab shows favorable signs, compliance expenditures remain high.
Ms. Le Hang noted that surpassing the 12-billion-USD export milestone in 2026 remains attainable if demand in China–Hong Kong holds firm and peak-season orders face no major disruptions. However, Q4 growth velocity will likely trail that of the first 8 months.
Source: Tap chi Kinh te - Tai chinh
Related Articles

Many Vietnamese agricultural products capture nearly half of Sweden’s market share
08/10/2026

Shrimp exports to the EU decelerate: How are Vietnamese enterprises adapting?
08/10/2026

Common fish transforms into an export commodity, helping Mekong Delta farmers hold their ground at home
08/10/2026

Seafood exports: Enterprises prepare for a tougher scenario
08/10/2026